Friday, November 20, 2026
Mitmunk
  • Home Improvement
  • Finance
  • Lifestyle
  • Business
  • Seo Digital
  • Auto
  • Law
  • Health
  • Other
    • Travel
    • Outdoor
    • Fashion
    • Entertainment
    • Construction
    • Education
    • Tech
    • Pet
    • Real Estate
No Result
View All Result
  • Home Improvement
  • Finance
  • Lifestyle
  • Business
  • Seo Digital
  • Auto
  • Law
  • Health
  • Other
    • Travel
    • Outdoor
    • Fashion
    • Entertainment
    • Construction
    • Education
    • Tech
    • Pet
    • Real Estate
No Result
View All Result
MitMunk
No Result
View All Result
Home Finance
The Hidden Costs of Quick Cash: Why Short-Term Fixes Can Hurt Long-Term Stability

The Hidden Costs of Quick Cash: Why Short-Term Fixes Can Hurt Long-Term Stability

Share on FacebookShare on Twitter

In an era where everything from groceries to rent feels more expensive than it did just a year ago, households are struggling to keep up. For many, one unexpected bill can tip the balance. The car breaks down, a child gets sick, or rent increases, and suddenly the numbers in the bank account no longer add up.

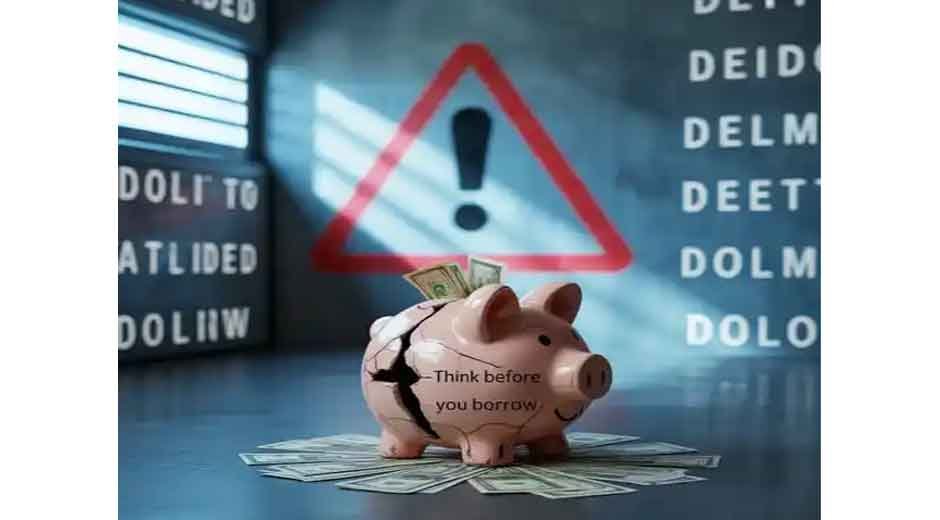
When emergencies hit, fast money becomes tempting. Short-term loans, cash advances, and similar products market themselves as immediate lifelines. But behind the promise of speed and convenience lies a deeper question: do these loans actually solve the problem, or do they simply delay the inevitable?

The most striking example is the payday loan, a small, short-term advance due in full by the borrower’s next paycheck. While it seems like a way to bridge the gap, high fees and lump-sum repayment requirements often pull people deeper into financial trouble.

Table of Contents

Toggle
  • Why People Choose Quick Money
  • The Trap of Repetition
  • Who Carries the Burden?
  • The Role of Regulation
  • Alternatives Taking Shape
  • Building Personal Resilience
  • Beyond the Household
  • Conclusion

Why People Choose Quick Money

The popularity of short-term credit highlights a harsh truth: millions of people live paycheck to paycheck. Saving for emergencies is a luxury many can’t afford. When rent is due or medical prescriptions need filling, there is little time to wait for bank approvals or family assistance.

The immediacy of a quick loan feels like the only option. Borrowers often think, “I’ll just pay it back with my next check.” But the challenge comes when life doesn’t cooperate—when another expense appears before the first is fully paid.

The Trap of Repetition

A short-term loan may solve today’s issue but can create tomorrow’s crisis. Because repayment often requires a lump sum, borrowers end up rolling over loans or taking out new ones. What started as a $300 advance quickly becomes a cycle of debt costing far more than the original bill.

This is what economists call the “debt spiral.” Once caught in it, breaking free is difficult. Money that should go toward essentials—food, housing, transportation—ends up feeding interest payments instead.

Who Carries the Burden?

The weight of short-term borrowing falls hardest on those already stretched thin. Lower-income workers, single parents, and gig-economy earners are particularly vulnerable. These groups often lack access to traditional credit or savings and may turn to a payday loan as a last resort when emergencies strike. But the toll goes beyond money. Constant stress from debt can strain family relationships, harm mental health, and reduce workplace productivity. In effect, financial instability spills into nearly every aspect of daily life.

The Role of Regulation

Governments have attempted to limit the harm of high-cost borrowing. Some regions cap interest rates or restrict how often loans can be rolled over. Others mandate clearer disclosures so borrowers understand the true cost of credit.

Yet regulation alone cannot erase demand. For many households, removing access to short-term loans entirely would leave them with no options at all. Policymakers walk a fine line between protecting consumers and preserving access to emergency funds.

Alternatives Taking Shape

To balance the equation, alternatives are beginning to emerge:

  • Credit unionsoffer small-dollar loans at lower interest rates, often designed specifically to replace high-cost credit.
  • Employer-based solutionslike earned wage access allow workers to tap into already-earned income before payday.
  • Technology-driven platformsare experimenting with microloans, budgeting tools, and financial wellness apps that combine education with lending.
  • Community-based models, including lending circles and nonprofit programs, help spread risk and provide affordable access to credit.

While these solutions are not yet universal, they point toward healthier ways to manage emergencies without compounding debt.

Building Personal Resilience

Ultimately, the strongest defense against reliance on high-cost loans is personal financial resilience. That doesn’t mean everyone can save thousands of dollars overnight, but small steps can make a difference:

  • Start with a micro emergency fund.Even $100 set aside can cover minor surprises and prevent the need for borrowing.
  • Track expenses closely.Awareness of where money goes can free up small amounts for savings.
  • Ask employers about assistance.Some companies quietly offer payroll advances or hardship programs.
  • Seek financial education.Community workshops and online resources can demystify credit and reduce reliance on short-term fixes.

Beyond the Household

This is not just a personal challenge—it’s a societal one. Rising inequality, wage stagnation, and high housing costs all fuel demand for quick-cash products. Until these structural issues are addressed, households will continue to face impossible choices between immediate relief and long-term harm.

Communities, employers, and policymakers each have a role to play. Building better safety nets, expanding access to affordable credit, and supporting financial literacy are all steps that reduce dependence on risky borrowing.

Conclusion

Quick-cash solutions are here to stay, but they come at a cost. Used sparingly, they may help bridge a gap. Used repeatedly, they can trap borrowers in cycles of debt that are difficult to escape.

The challenge lies in shifting from reactive borrowing to proactive resilience. By preparing for emergencies, embracing safer alternatives, and demanding systemic change, individuals and societies alike can reduce the reliance on short-term fixes.

Because what starts as a small payday loan taken in desperation too often grows into a lasting struggle. Breaking that pattern requires not just personal discipline but collective effort to ensure financial stability for all.
Related Posts

Defining What Winning

Defining What Winning Means to You

by Emily Stevens
November 19, 2026
0

Winning does not always look like a bigger paycheck, a perfect house, or a milestone you can show off online...

Trust-as-Financial-Currency

Trust as Financial Currency

by Emily Stevens
November 2, 2026
0

Money Works Because We Agree That It Works A banknote is a small piece of printed material. A number in...

Payment-History-Carries-Real-Weight

Payment History Carries Real Weight

by Emily Stevens
October 25, 2026
0

Why the Smallest Bill Can Tell the Biggest Story A lot of people think credit health is mainly about how...

POPULAR NEWS

Delores Miller Clark

Delores Miller Clark: Learn More about John List’s Ex-Wife

September 27, 2022
Deserai Anderson Utley Personal Life, Career, & More

Deserai Anderson Utley Personal Life, Career, & More

September 30, 2022
Lisa Seal Frigon

Lisa Seal Frigon: All about Drug Lord Barry Seal’s Daughter

September 18, 2022
Linnell S. Nobori

Linnell S. Nobori: All there is to Know about Ted Bessell’s Wife

September 5, 2022
Gweneth Gonzales Thomas

What You May Not Know About Gweneth Gonzales Thomas, Richard Thomas’ Daughter

August 2, 2022

EDITOR'S PICK

Professional Roofing Company

Why Choose a Professional Roofing Company?

March 26, 2024
Leveraging AI Voice-Over Generators

Leveraging AI Voice-Over Generators to Enhance Customer Support Services: From Interactive Voice Response (IVR) to Virtual Assistants

September 15, 2024
kate elizabeth lando

Everything About Kate Elizabeth Lando

May 29, 2022
In today's digitally-driven business landscape, organizations are striving to stay ahead of the curve, and they often do so by seeking support from business process outsourcing (BPO) services. Among the myriad of options available, the BPO industry in the Philippines stands as a robust contender due to its numerous advantages. Firstly, the nation presents a rich pool of talented professionals who are proficient in English and have a deep understanding of Western culture. This combination ensures that customer interactions are not just transactional but are also culturally nuanced and efficient. This has been a significant factor contributing to the success of call center services in the Philippines. Secondly, the competitive cost structure of the Southeast Asian archipelago makes it an attractive outsourcing destination. When compared to other countries, businesses can save substantially on operating costs, making the country a viable choice for companies looking to optimize expenses without compromising on quality. The Philippine BPO industry also benefits greatly from the government's proactive approach. Through various initiatives and policies designed to attract foreign investments, the nation has been able to foster a conducive environment for the growth and development of the BPO sector. Apart from this, one of the defining features of the nation's outsourcing sector is its adaptability and scalability. As customer service demands fluctuate, businesses can adjust their service requirements accordingly, ensuring optimum utilization of resources. Outsourcing non-core business functions such as customer support to BPOs allows companies to focus their resources on strategic areas that drive growth and innovation. This reallocation of resources can significantly improve a company's operational efficiency and productivity. Moreover, BPOs use cutting-edge technology and adhere to best practices to deliver high-quality customer service. They keep pace with the changing trends and expectations in the customer service industry, ensuring that businesses can provide top-notch customer experiences consistently. For companies seeking to enhance their customer experiences through outsourcing, the Philippines offers an excellent blend of talent, cost-effectiveness, and quality. With the continued support from the government, a skilled workforce, and a customer-centric approach, the future of call center outsourcing to the country looks promising. Furthermore, the nation's BPO sector also excels in lead generation. As part of their comprehensive service offerings, many BPOs in the country provide lead generation services, helping businesses expand their customer base and drive growth. Given these compelling advantages, it's no surprise that it is quickly becoming a go-to destination for global businesses looking to outsource their BPO services. The robustness of the BPO industry in the Philippines is also due to its impressive technological infrastructure. The industry has been keen on adopting the latest technologies to enhance the efficiency and effectiveness of its services. This includes the implementation of AI and automation in various processes to streamline operations, increase productivity, and improve customer service quality. The continuous technological advancement ensures the Philippine BPO industry stays competitive in the global landscape. There's a strong focus on employee welfare. The work culture emphasizes personal growth, career development, and employee satisfaction, leading to a motivated workforce that is committed to providing excellent customer service. This focus on human capital is a crucial factor behind the consistently high performance of the industry. An often-overlooked advantage of the Philippines as an outsourcing destination is its strategic geographic location. Being in a time zone that is compatible with many Western countries enables it to offer 24/7 customer service, meeting the needs of global businesses and customers in real time. Language proficiency is not confined to English alone. There is a multilingual capability in the local workforce that can cater to non-English speaking markets, adding a vital edge in today's multicultural global marketplace. The Southeast Asian nation has been proactive in ensuring data security and compliance, a critical concern for businesses outsourcing their operations. Rigorous data protection measures, adherence to international standards, and stringent privacy laws demonstrate the country's commitment to safeguarding business and customer data. With its strategic mix of highly skilled talent, competitive costs, advanced technology, supportive government policies, and a strong emphasis on quality and data security, the Philippines has rightfully earned its reputation as a top-notch outsourcing destination. It has successfully positioned itself as a powerhouse in the global BPO landscape, promising a bright future for businesses that choose to partner with it.

Navigating the Digital Era with Philippine BPO Services

June 13, 2023
Contact Us: Info@mitmunk.com

© 2022 Mitmunk Theme Copyright

No Result
View All Result
  • Homepages
    • Home Page 1
  • Business
  • Entertainment
  • Fashion
  • Health
  • Lifestyle
  • Tech
  • Travel

© 2022 Mitmunk Theme Copyright